Dental care can be surprisingly expensive for older adults. Finding suitable dental insurance during retirement may feel overwhelming.
Limited income makes comparing coverage important. This guide explains senior dental plans, their costs, benefits, limitations, and alternatives.
Why Dental Insurance Matters for Seniors
Retirees may need more dental care as gum disease, tooth loss, and other concerns develop with age. Preventive visits identify problems early, while coverage may reduce worries and discourage missed appointments.
Main Types of Dental Insurance for Seniors
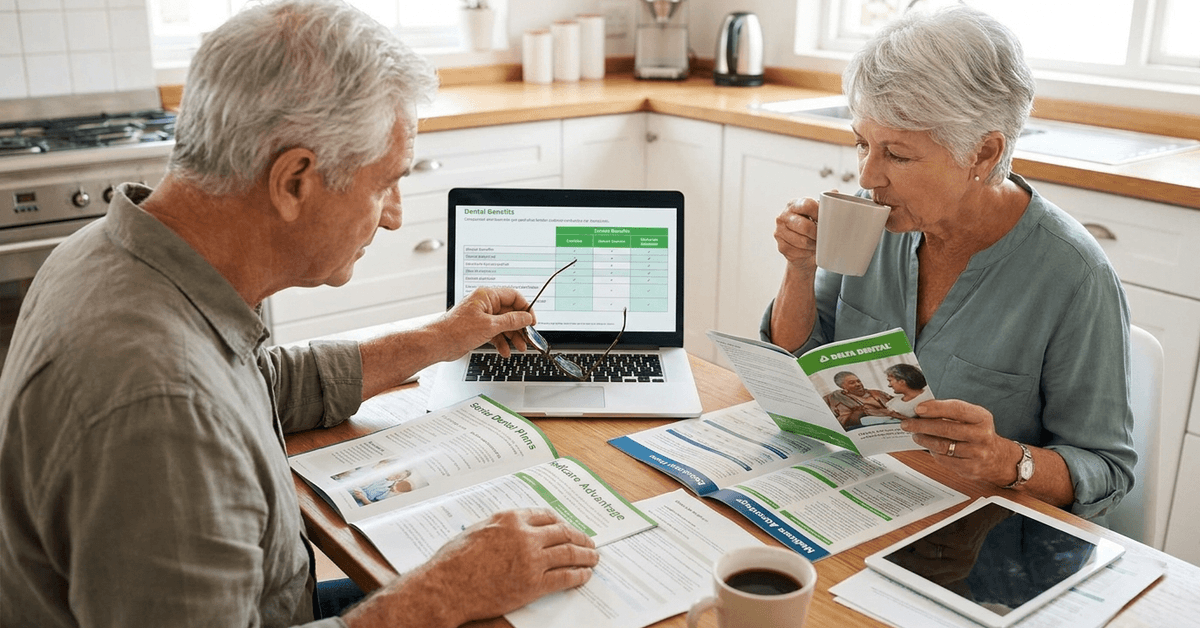
Seniors comparing dental coverage find plans with different costs and rules. Understanding these options helps identify which arrangement may suit individual needs and budgets.
Traditional Dental Insurance Policies
Traditional policies resemble employer-sponsored dental insurance, with premiums and dentist networks.
Preventive services are often covered fully or nearly fully, while fillings and crowns may require coinsurance. Annual benefit limits are common, though some insurers allow benefit rollovers.
Dental Discount Plans
Dental discount plans charge a membership fee in exchange for negotiated prices at participating practices. These programs provide reduced rates rather than insurance reimbursement, without deductibles, claims, or annual maximums.
Although membership costs may be lower than insurance premiums, extensive dental treatment can still create substantial expenses.
Medicare Advantage with Dental
Original Medicare generally excludes routine dental care, with exceptions for covered medical treatment. Many Medicare Advantage plans include dental benefits or optional additions, sometimes covering dentures or other extensive procedures.
Benefits differ by plan, so review exclusions, provider networks, waiting periods, and treatment limits before enrolling.
Stand-Alone Senior Dental Plans
Private insurers and some dental organizations offer stand-alone policies designed around older adults' needs. Their covered services may include preventive visits, periodontal care, bridges, and dentures, depending on the contract.
PPO, HMO, and indemnity arrangements vary in dentist choice, payment rules, and how much members pay themselves.
What to Consider When Choosing Dental Insurance
The right plan depends on expected treatment, preferred dentists, and available income. Examining coverage can prevent misunderstandings and unexpected bills during treatment.
Coverage for Major Dental Procedures
Some older adults need only cleanings and X-rays, while others require crowns, root canals, or dentures.
Major procedures may receive limited reimbursement or involve higher coinsurance than preventive care. Compare service categories and exclusions carefully to understand remaining expenses.
Annual Maximums and Waiting Periods
Many policies limit yearly insurance payments, sometimes to approximately $1,000 to $2,000. After reaching the annual maximum, patients generally pay additional covered treatment costs themselves.
New policies may also impose waiting periods for major procedures, ranging from several months to more than a year.
Network Limitations
Some insurance policies require members to visit participating dentists to obtain their best benefits. Checking provider networks matters especially when keeping your dentist or visiting specialists.
Discount programs can also restrict participating offices, although network sizes differ considerably between providers and locations.
Premium Costs and Out-of-Pocket Expenses
Overall dental expenses include premiums, deductibles, copays, and coinsurance rather than monthly charges alone. A higher premium sometimes brings better benefits, while cheaper coverage may leave larger bills after treatment.
Comparing realistic yearly costs can help budget-conscious seniors decide whether insurance or a discount arrangement is preferable.
Comparing Popular Senior Dental Insurance Plans
Providers include Delta Dental, Humana, Cigna, Aetna, and UnitedHealthcare. These illustrative figures show possible differences, though actual terms require confirmation.
| Provider | Plan Type | Typical Monthly Cost | Annual Maximum | Major Services |
|---|---|---|---|---|
| Delta Dental | PPO | $30–$50 | $1,000–$2,000 | 50% after deductible |
| Humana | Loyalty (PPO) | $25–$45 | $1,000–$1,500 | Varies by year |
| Cigna | Dental 1500 | $30–$55 | $1,500 | 50% after 12 months |
| UnitedHealthcare | Medicare Advantage | Varies | $1,000–$2,500 | Sometimes coverage for dentures |
Prices and benefits depend on location, age, policy details, and enrollment circumstances. Some insurers also provide additional services such as teledentistry or wellness discounts, which may appeal to particular members. Confirm exact benefits in current plan documents before comparing final costs.
Alternatives if Dental Insurance Isn’t Right for You
Insurance is not the best option for every retiree. People needing limited care or seeking predictable expenses may prefer one of these alternatives.
Direct Payment to Dentists
Some patients pay dentists directly without purchasing an insurance policy. Practices occasionally offer cash discounts, although reduced fees are not available everywhere.
Paying directly may suit occasional checkups, but major procedures can become costly without insurance assistance or another financial arrangement.
In-House Dental Memberships
Certain dental offices offer memberships covering routine cleanings and examinations for an annual fee. These practice memberships may also discount additional procedures without operating as insurance.
Their straightforward terms can appeal to some seniors, although benefits normally apply only at the participating practice.
Community Health Resources
Older adults with limited incomes may find low-cost services through clinics, nonprofits, or local health departments. Programs provide reduced-cost care, but eligibility, appointment availability, and funding differ by community.
The American Dental Association's Find-a-Dentist tool can help locate dentists, while local agencies may identify affordable programs.
Key Tips for Maximizing Dental Insurance Benefits
Making good use of existing coverage involves planning visits and understanding policy limits. These practices help seniors manage costs and avoid billing problems.
- Schedule regular checkups to identify problems before treatment becomes more expensive.
- Review covered services and exclusions before agreeing to major procedures.
- Request written cost estimates from your dentist before starting treatment.
- Consider spreading nonurgent procedures across benefit years when annual maximums apply.
- Save receipts and records to support questions or appeals involving denied claims.
Frequently Asked Questions About Senior Dental Plans
Seniors often have similar questions about Medicare, existing conditions, and family enrollment. Answers depend on each provider’s policy terms.
Does Medicare cover dental care?
Original Medicare generally does not cover routine cleanings, fillings, dentures, or most dental treatments. Limited medical exceptions apply when certain dental services are connected to covered medical care.
Medicare Advantage plans may include dental benefits, but covered procedures and payment limits vary considerably.
Are pre-existing dental conditions covered?
Some private policies restrict benefits for existing dental problems or expensive services during early coverage periods.
Waiting periods and exclusions differ, so similar-looking plans may handle the same treatment differently. Reading detailed policy documents before enrollment can help avoid unexpected out-of-pocket costs.
Can spouses or partners join a single plan?
Some providers let spouses or other family members enroll together through eligible policy arrangements. Joint enrollment may simplify administration or offer savings, although discounts are not guaranteed.
Check membership rules, dependent eligibility, and combined costs before deciding whether separate policies would work better.
Conclusion
Finding suitable senior dental coverage requires comparing benefits, limitations, and total costs. Traditional insurance, discount plans, and Medicare Advantage options address different needs.
Review available providers and ask questions before committing to a policy. Thoughtful planning can support ongoing dental care without overlooking retirement budget priorities.