Choosing a loan is an important financial decision for unexpected expenses, existing debts, and larger planned personal purchases, or a planned project. This guide explains how online loans work and why people compare them.
It also covers benefits, risks, costs, and common application steps. These points support better choices before a new repayment obligation.
Why Online Loans Are Becoming So Popular?
Online lending has made researching and applying for credit more accessible online. The appeal comes from digital convenience and choice, although approval standards vary.
Convenience and Speed
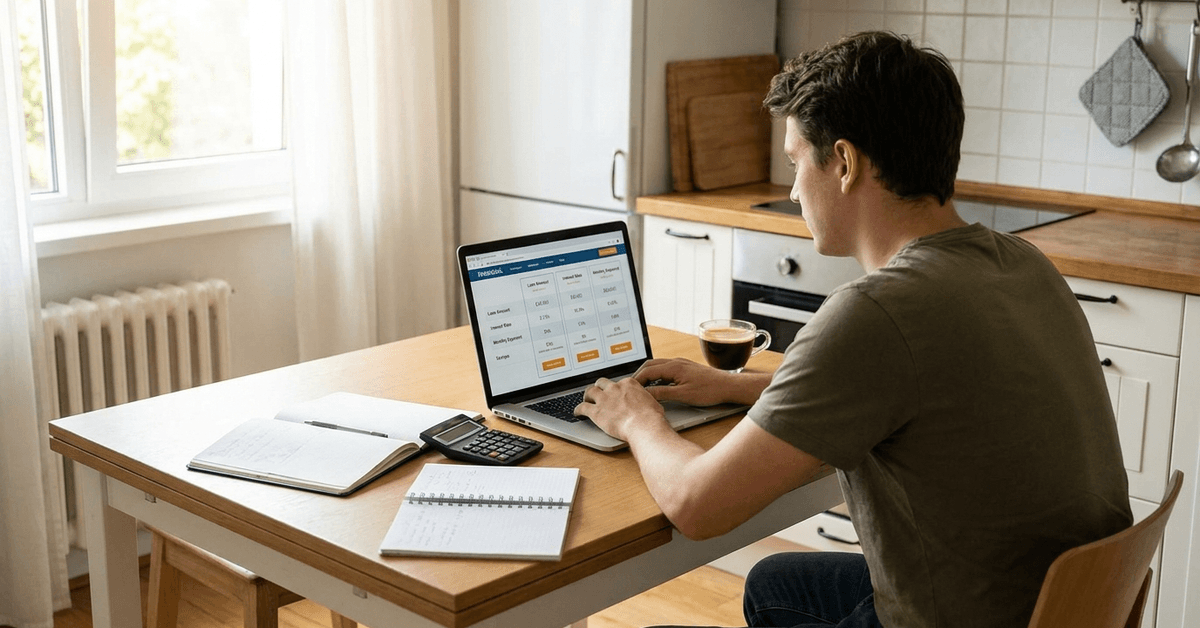
Online applications allow borrowers to submit information without visiting a branch. Automated systems can provide faster preliminary decisions, but final approval may require verification. Funding speed also depends on the lender, banking process, and application details.
Comparing Diverse Loan Offers
Digital platforms can make it easier to review several loans online. Borrowers can compare rates, repayment terms, fees, and available amounts before choosing.
Comparing similar amounts and durations helps prevent a low payment from hiding a longer commitment.
Flexible Eligibility Requirements
Online lenders do not all use identical qualification standards. Some consider income, employment, credit information, bank activity, or other financial risk factors alongside credit scores. Different criteria may broaden options, but approval is not guaranteed.
How Do Online Loans Actually Work?
Most online loans move through application, verification, assessment, acceptance, and funding. Understanding each digital lending stage can reduce rushed decisions.
Initial Application
Applicants usually complete a form on the lender's official site or app. Information can include identity, income, employment, address, and banking details. Accurate entries reduce delays from incomplete information.
Credit and Background Checks
Lenders evaluate whether applicants meet lending requirements. They may review credit reports, income, debts, or account information. The exact checks and credit-report effects vary by provider.
Receiving Offers and Accepting Terms
Approved applicants generally receive an offer showing the amount, interest rate, fees, payment schedule, and conditions.
Reading the complete loan disclosure is essential before accepting. Borrowers should compare final terms with earlier information and ask about differences.
Funding and Repayment
After acceptance and final verification, lenders send funds using the agreed method. Repayment generally follows scheduled installments through automatic debit or another approved payment method. Borrowers should plan for due dates and keep records.
Key Advantages of Comparing Loans Online
Online comparison can help borrowers gather information without choosing the first offer. The main benefits involve visibility, competition, and access when information is current.
- Transparency: Rates, fees, amounts, and repayment periods can often be reviewed before applying.
- Competition: Comparing providers may reveal meaningful differences in costs and conditions.
- Convenience: Research can be completed without multiple branch appointments.
- Availability: Digital tools can be accessed outside normal banking hours.
- Planning: Calculators can help estimate installments and total repayment.
Potential Drawbacks and Precautions
Digital access does not remove the financial risks of borrowing. Applicants should consider cost, security, and credit impact before applying or sharing information.
Interest Rates and Fees
A low advertised interest rate may not represent the full borrowing cost. The Consumer Financial Protection Bureau explains that APR can include interest plus certain fees, making APR comparison useful when comparing offers. Also review origination charges, late fees, and total repayment.
Online Scams and Security
Fraudulent websites and messages can imitate real financial companies. Borrowers should use official digital channels, verify contacts, and protect passwords or verification codes.
Guaranteed-approval promises or unusual advance-payment requests deserve caution.
Impact on Credit Score
Credit inquiries do not all affect credit files the same way. A lender may use a soft inquiry initially and a hard inquiry later, depending on the product. Applicants should confirm the credit-check process before several formal applications.
Steps to Compare and Choose an Online Loan Wisely
A structured comparison keeps attention on affordability rather than advertising. Each loan selection step should help determine whether borrowing fits the applicant's situation.
1. Define Your Purpose
Identify why the funds are needed and the required amount. A defined purpose helps prevent unnecessary overborrowing when a larger limit is offered. It also makes comparing suitable loan types and terms easier.
2. Review Multiple Lenders
Compare established lenders using the same amount and term. For example, SoFi provides an official online personal-loan page where eligible U.S. applicants can review product information. Comparing providers reveals differences in rates, fees, eligibility, and features.
3. Calculate Total Loan Costs
Interest is only one part of what a borrower pays. The CFPB notes that personal installment loans can include fees that increase the overall borrowing cost. Compare APR, fees, monthly payments, duration, and total repayment before accepting.
4. Examine Repayment Flexibility
Repayment features can matter if finances change. Check whether the contract permits early repayment, extra payments, or payment-date changes. Understand any fees or conditions for these features.
5. Check for Security and Regulation
Confirm that a lender operates legally where the borrower lives. Use official regulatory resources when available. Privacy notices, secure login procedures, and customer support deserve review.
Popular Types of Online Loans Compared
Online borrowing includes products for different needs and terms. Comparing loan structure and security prevents treating every digital product as interchangeable.
| Type | Typical Use | Payment Terms | Key Consideration |
|---|---|---|---|
| Personal Loans | General borrowing | Installments | Fixed or variable costs |
| Debt Consolidation | Combining debts | Installments | Compare new total cost |
| Payday Loans | Short-term needs | Very short term | Potentially high cost |
| Auto Loans | Vehicle purchase | Installments | Vehicle may secure loan |
Common Questions When Comparing Loan Platforms
Borrowers often have similar questions about applications, funding, and repayment. Checking provider-specific answers matters because policies differ.
- Does applying require a hard credit check? It depends on the lender and application stage.
- Can funds arrive the same day? Some providers offer fast funding, but timing is not guaranteed.
- Are online-only lenders trustworthy? Many legitimate lenders operate online, but credentials should be verified.
- How do repayments work? Scheduled installments are common, although payment methods differ.
- Can terms change after prequalification? Preliminary estimates may change after final underwriting.
Risks and Responsible Borrowing
Every loan creates an obligation that affects future income, savings goals, emergency reserves, and household expenses over time.
Responsible use means checking monthly affordability and considering alternatives before taking costly credit, including whether the payment remains manageable after rent, food, utilities, insurance, transportation, and existing debt obligations are paid each month.
Conclusion
Online loans can make credit comparison easier through digital channels. Convenience should still be weighed against APR, fees, security, credit effects, and repayment obligations.
Comparing providers and reviewing complete loan terms can reduce surprises. The strongest choice is a loan that serves a clear purpose and fits a realistic repayment budget.