A $10,000 personal loan at 12% interest looks painless at $222 per month over five years. Stretch that math to the finish line, though, and you have paid roughly $13,300 total.
Most borrowing guides gloss over that gap between the monthly number and the final receipt. The difference between those two figures, often $2,000 to $3,000 on a modest loan, sits in the fine print of every offer.
This guide on personal financing is for the first-time borrower in their mid-20s staring at a loan application and wondering why every option seems designed to confuse. If that's you, this piece was built from the numbers up.
What Personal Financing Looks Like Right Now
Personal financing covers three main products: personal loans, credit cards, and lines of credit. All three give you access to borrowed money. But they charge differently, repay differently, and punish mistakes differently.
The average personal loan interest rate sits at about 12.41% as of mid-2026, according to Bankrate's monitor data.
Credit cards, on the other hand, average roughly 21% to 23% APR depending on the source. That spread matters more than most guides let on.
Personal Loans: Fixed and Predictable
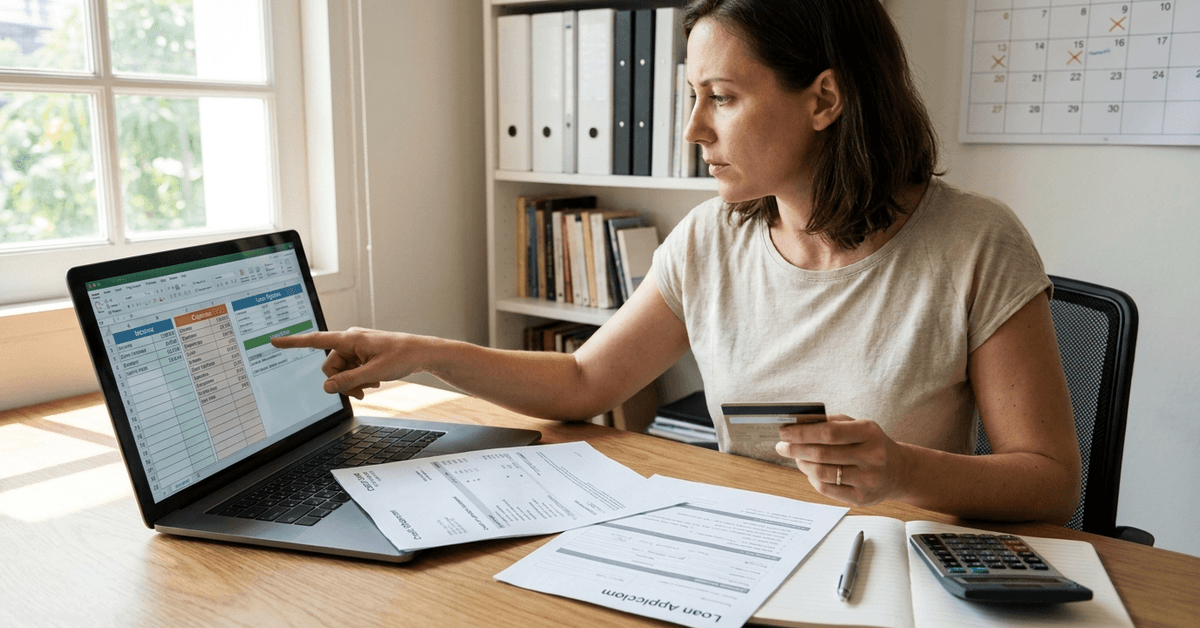
A personal loan gives you a lump sum. The repayment schedule is fixed: same payment each month for a set number of months, usually 24 to 60. The interest rate can be fixed or variable, though most borrowers get fixed rates.
One thing I would flag about personal loans at Bankrate's current 12.41% average: that rate assumes a 700 FICO score and a three-year term. Drop to a 620 score or stretch to five years, and the offer changes fast.
Credit Cards: Flexible but Expensive
Credit cards let you borrow and repay on a revolving basis, up to a set limit. The flexibility is real. So is the cost: average credit card APR hit 23.89% in Q2 2026 according to CardRatings data.
Minimum payments on credit cards are designed to keep you in debt longer. A $5,000 balance at 22% with minimum payments can take over 20 years to clear.
Lines of Credit: The Middle Ground
A line of credit works like a flexible loan. Borrow what you need, repay it, borrow again. Variable interest rates are the norm, which means the monthly cost shifts without warning.
Lines of credit make sense for ongoing or unpredictable expenses. They make less sense for one-time purchases where a fixed-rate personal loan locks in the cost.
The Application Process Lenders Don't Simplify
Applying for any personal financing product follows a pattern: submit information, wait for a credit check, get a decision. The form takes ten minutes. The factors behind the decision take longer to understand.
What Lenders Evaluate Beyond Credit Score
Credit score grabs all the attention. A 740+ FICO gets you closer to the lowest advertised rates. But lenders check more than that one number.
Debt-to-income ratio (DTI) is the metric most first-time borrowers have never calculated. Add up monthly debt payments, divide by gross monthly income. A DTI above 40% sends a clear signal to lenders, and the response is usually a higher rate or a rejection.
Steady employment history matters, too. A gap in income or a recent job switch can shift the terms of an offer, even when the credit score is solid.
The Origination Fee Nobody Reads
Many online lenders charge an origination fee between 1% and 8%, deducted directly from the loan amount. Borrow $10,000 with a 5% origination fee, and $9,500 hits your account.
The remaining $500 goes to the lender before you make a single payment. That fee is folded into the APR calculation, but the advertised "interest rate" on the landing page often leaves it out.
Two lenders showing the same rate can deliver very different actual costs depending on origination fees. Always compare APR to APR, never rate to rate.
Comparing Personal Financing Offers Side by Side
The differences between these three products become clearer when you line them up against the same criteria. Here is a quick comparison based on mid-2026 averages:
| Feature | Personal Loan | Credit Card | Line of Credit |
|---|---|---|---|
| Average Interest Rate (2026) | 12–14% | 21–24% | 10–18% (variable) |
| Repayment Structure | Fixed monthly payments | Minimum payments, revolving | Flexible draw and repay |
| Typical Term | 2–7 years | Ongoing | 1–5 years (draw period) |
| Origination Fees | 0–8% | None (but annual fees possible) | Possible |
| Best For | One-time large expense | Daily spending, short-term float | Ongoing variable costs |
The takeaway: personal loans cost less in interest on a lump-sum need, but credit cards offer unmatched flexibility for smaller, recurring charges paid in full each month.
Fees That Stack Up Quietly
The sticker rate is never the full cost. A few fees first-time borrowers tend to miss:
- Late payment penalties: typically $25 to $40 per missed payment, and some lenders raise your rate after two consecutive misses
- Early repayment charges: less common in 2026, but still present at some banks and credit unions
- Annual fees on credit cards: the average annual fee reached $234.77 at the end of H1 2026 for cards that charge one
Reading Reviews the Right Way
Company websites curate their own testimonials. Independent review platforms like the CFPB complaint database or Trustpilot tend to surface patterns that marketing pages hide.
Look for repeated complaints about the same issue, not one-off bad experiences.
Why I Think the "Lowest Monthly Payment" Advice Gets It Backward
A popular piece of guidance for first-time borrowers says to pick the longest loan term so the monthly payment stays comfortable. I think that advice costs borrowers real money, and the math backs it up.
A $10,000 personal loan at 12% over three years costs roughly $1,957 in total interest. The same loan stretched to five years drops the monthly bill by about $110 but adds approximately $1,390 in extra interest.
That $110 per month in "savings" generates $1,390 in additional cost. My take: borrowers who can manage the higher three-year payment at the Bankrate average of 12.41% should take the shorter term every time. The discomfort lasts 36 months. The savings last forever.
The exception is when the borrower has no emergency cushion. A lower payment with a six-month emergency fund already in place makes sense. But stretching a term purely for comfort, without accounting for total cost, is the most expensive form of financial comfort available.
Strengthening a Borrowing Profile Takes Months, Not Days
Approval odds and interest rates don't change overnight. A few habits matter more than any single action.
Check Credit Reports for Errors
Credit report errors affect roughly 1 in 5 consumers. Disputing an inaccurate late payment or a duplicate account can move a score meaningfully. Free reports are available weekly through AnnualCreditReport.com.
Pay Down Existing Balances First
Reducing credit card utilization below 30% of available credit tends to produce the fastest score improvements. A $3,000 balance on a $10,000 limit sits right at that threshold.
Build a Small Buffer Before Borrowing
Lenders don't ask about emergency funds directly. But a borrower with three months of expenses saved is less likely to miss payments during a job transition or unexpected medical bill. That stability shows up indirectly in on-time payment history over the following year.
Questions People Ask About Personal Financing
These are the searches that come up most for first-time borrowers, with answers that add to the detail above.
- Q: Can I get a personal loan with a credit score below 600?
Some lenders approve scores as low as 560, though rates at that level often exceed 25% or higher. Secured loans or a co-signer can bring the rate down, but both carry their own risks: collateral loss or strained relationships. - Q: How long does personal loan approval take in 2026?
Online lenders like SoFi or Upstart often issue decisions within minutes. Funding typically arrives in one to three business days. Credit unions and traditional banks may take a week or longer, especially for larger amounts. - Q: Does applying for multiple loans hurt my credit score?
Multiple hard inquiries within a 14-day window for the same loan type usually count as a single inquiry for scoring purposes. Spreading applications over several weeks, though, stacks separate hits on the report.
Conclusion
Borrowing for the first time should start with total cost, not monthly payment. A three-year term at 12% interest on $10,000 saves roughly $1,390 compared to five years.
Origination fees, DTI ratios, and credit report errors shape the real offer more than any advertised rate. The smartest first-time borrowers compare APR, question the default term, and build a buffer before signing anything.